
“Most founders walk into a pitch room with a valuation they picked from thin air — and investors know it the moment they hear it. The founders who raise on their own terms are the ones who understand exactly how the other side of the table arrives at a number.”
Valuation is the most misunderstood number in startup fundraising. Founders either undervalue themselves out of fear, or overvalue themselves out of ambition — and both mistakes cost equity, time, and credibility.
This guide teaches you how to value a startup the way experienced investors actually do it: not with magic formulas, but with a structured reading of signals, comparables, and risk. By the end, you will know exactly which methodology fits your stage, what factors move your number up or down, and the one thing investors look at first that most founders never even think about.
$16M
Median seed-stage valuation globally in 2026 (Crunchbase)
42%
Valuation premium AI startups receive at seed stage vs peers
15–20%
Standard equity dilution founders accept at seed and Series A
1. Why Valuation Matters More Than the Funding Amount
Founders often celebrate the amount raised — “we raised $2M!” — without paying enough attention to the valuation at which they raised it. But the valuation determines something far more important: how much of your company you gave away.
Consider two founders raising the same amount:
| Founder | Amount Raised | Pre-Money Valuation | Equity Given Away | Your Remaining Stake |
|---|
| Founder A | $2M | $6M | 25% | 75% |
| Founder B | $2M | $12M | 14.3% | 85.7% |
Same round size. Same investor. But Founder B kept an extra 10.7% of their company — simply by understanding and defending their valuation. On a $100M exit, that difference is worth over $10 million. That is not a rounding error. That is the cost of not preparing.
💡 The Core Insight
Valuation is not about what your startup is worth today. It is about what story you can credibly tell about what it will be worth — and how well you back that story with data. Investors do not buy the present. They buy the future. Your job is to make that future feel inevitable.
2. What Investors Actually Read Before Naming a Number
Before any methodology enters the conversation, experienced investors run a fast mental checklist the moment you walk in. This is the part no pitch coach talks about openly — but understanding it changes everything about how you prepare.
🧠 The Investor’s First-Pass Signal Checklist
👥
Team Density
Have these founders solved hard problems before? Do they carry unfair domain advantages no one else has?
📊
Market Signal
Is this a real growing market — or are they trying to create demand that does not yet exist?
🔁
Traction Shape
Not just the number — is the growth curve accelerating, flat, or quietly slowing down?
🛡️
Defensibility
What stops a well-funded competitor from copying this within the next 6 to 12 months?
💸
Unit Economics
Does the business become more efficient as it scales — or does each new customer cost more to serve?
🚪
Exit Clarity
Can the investor mentally picture a realistic $500M–$1B outcome within 7 to 10 years from today?
🔍 What Nobody Tells You
Experienced VCs often make a pre-valuation decision in the first 8 minutes of a meeting — based purely on how you talk about your competition, how you handle pushback, and whether you know your numbers cold without checking your deck. The actual valuation negotiation is downstream of that decision. If they have not decided you are the right founder, no methodology will save the number.
3. The 6 Valuation Methods — Which One Fits Your Stage
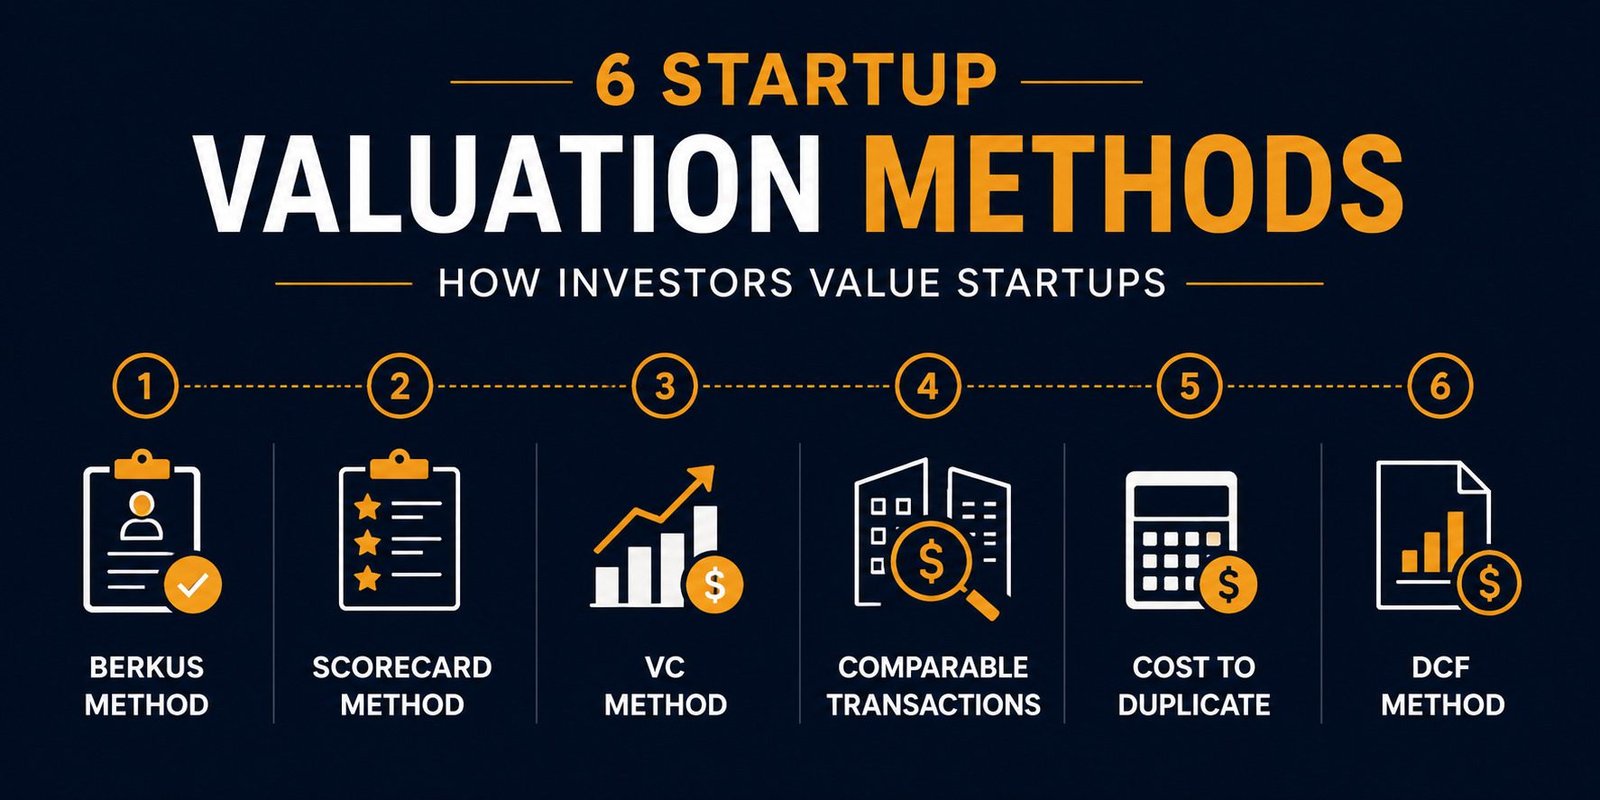
There is no single correct method to value a startup. Different stages require different frameworks. Using the wrong one signals inexperience. Here are the 6 methods used in real practice — when to apply each, and what choosing the right one signals to investors about your sophistication.
Method 01🔢 The Berkus Method
Developed by angel investor Dave Berkus, this assigns a maximum value to each of 5 qualitative milestones. It is designed specifically for pre-revenue startups where there is no financial data to anchor on.
| Milestone | Value Added (Up To) |
|---|
| Compelling idea / sound concept | $500,000 |
| Working prototype | $500,000 |
| Quality founding team | $500,000 |
| Strategic partnerships or relationships | $500,000 |
| Product rollout or initial sales | $500,000 |
Maximum pre-money valuation: $2.5M — though many modern investors adjust this ceiling to $5–8M given today’s market realities.
✅ Best for: Idea-stage and pre-MVP startups with no revenue. Works well when approaching angel investors.
Method 02📋 The Scorecard Method
Also called the Bill Payne Method, this compares your startup against the average pre-money valuation of similar funded startups in your region — then adjusts up or down based on weighted scoring of key factors.
| Factor | Weight | Scoring Range |
|---|
| Strength of the founding team | 30% | 0.0x to 1.5x |
| Size of the opportunity | 25% | 0.0x to 1.5x |
| Product and technology | 15% | 0.0x to 1.5x |
| Competitive environment | 10% | 0.0x to 1.5x |
| Marketing and sales channels | 10% | 0.0x to 1.5x |
| Need for additional investment | 5% | 0.0x to 1.5x |
| Other factors | 5% | 0.0x to 1.5x |
Multiply each factor score by its weight, sum all results, then apply the total multiplier to the regional average valuation for your stage.
✅ Best for: Pre-seed to seed stage startups with some early proof points but limited or no revenue.
Method 03💰 The VC Method
This is how most institutional VCs actually think about value — working backwards from a target exit. It answers one question: “If I invest X today and need Y return, what is the most I can pay right now?”
Example: A VC expects your startup to exit at $50M in 5 years and needs a 10x return. They will not pay more than $5M post-money today. If they invest $1M, your pre-money in their model is $4M — regardless of what you think you are worth.
💡
The Fund Size Rule Investors Never Explain
A $500M fund needs $500M+ in returns just to justify management fees. That means every investment must theoretically be able to return the entire fund — so they mentally need your exit to be $1B+. If your market cannot support a billion-dollar outcome, they will pass regardless of your valuation.
✅ Best for: Seed to Series A conversations with institutional venture capital firms.
Method 04🏢 Comparable Transactions
This method looks at what similar startups in your sector, stage, and geography recently raised — and at what valuation. It is the most grounding method because it anchors your ask to real market data rather than projections.
Where to find comps: Crunchbase, PitchBook, Tracxn, Venture Intelligence (India-specific), and recent accelerator cohort reports from YC, Sequoia Surge, and Elevation Capital.
Match these variables precisely when identifying comparables:
- Same funding stage — pre-seed, seed, or Series A
- Same broad sector — SaaS, fintech, agritech, deeptech
- Similar geography and addressable market size
- Raised within the last 12 to 18 months maximum
- Similar revenue range or equivalent traction milestone
✅ Best for: Any stage. Most powerful when used alongside a second method to cross-validate your number.
Method 05🔄 The Revenue Multiple Method
Once you have meaningful revenue — typically $10K MRR or above — investors shift from qualitative to quantitative methods. The most common approach is applying an industry multiple to your ARR.
Example: $500K ARR SaaS business in a growing vertical with strong net revenue retention → $500K × 8 = $4M pre-money. Add an AI layer with 120% NRR and that multiple stretches to 12–15x.
💡
Growth Rate Matters More Than Revenue Total
A startup at $500K ARR growing 15% MoM is worth significantly more than one at $1M ARR growing 3% MoM. Always show month-over-month growth rate alongside your absolute revenue — the curve tells more than the number.
✅ Best for: Revenue-generating SaaS or subscription businesses at seed stage and beyond.
Method 06🏗️ Cost to Duplicate
This method asks: how much would it cost someone to build exactly what you have built from scratch today? It covers R&D, engineering time, IP development, infrastructure, and early customer acquisition costs.
This gives you a valuation floor — the minimum any rational buyer should pay. It does not capture future value, so it is used alongside other methods rather than alone.
⚠️
Common Mistake With This Method
Founders often overcook the numbers — counting inflated hourly rates and speculative future work as past costs. Sophisticated investors will immediately challenge these figures. Only count documented, market-rate costs that are already spent.
✅ Best for: Deep tech, hardware, or biotech startups where building the core product is genuinely expensive and difficult to replicate.
Quick Reference: Which Method for Which Stage
| Method | Best Stage | Revenue Needed | Complexity |
|---|
| Berkus Method | Idea / Pre-MVP | No | Low |
| Scorecard Method | Pre-Seed / Seed | No / Minimal | Medium |
| VC Method | Seed / Series A | Optional | Medium |
| Comparable Transactions | Any Stage | Optional | Low–Medium |
| Revenue Multiple | Seed / Series A | Yes | Low |
| Cost to Duplicate | Pre-Seed | No | Medium |
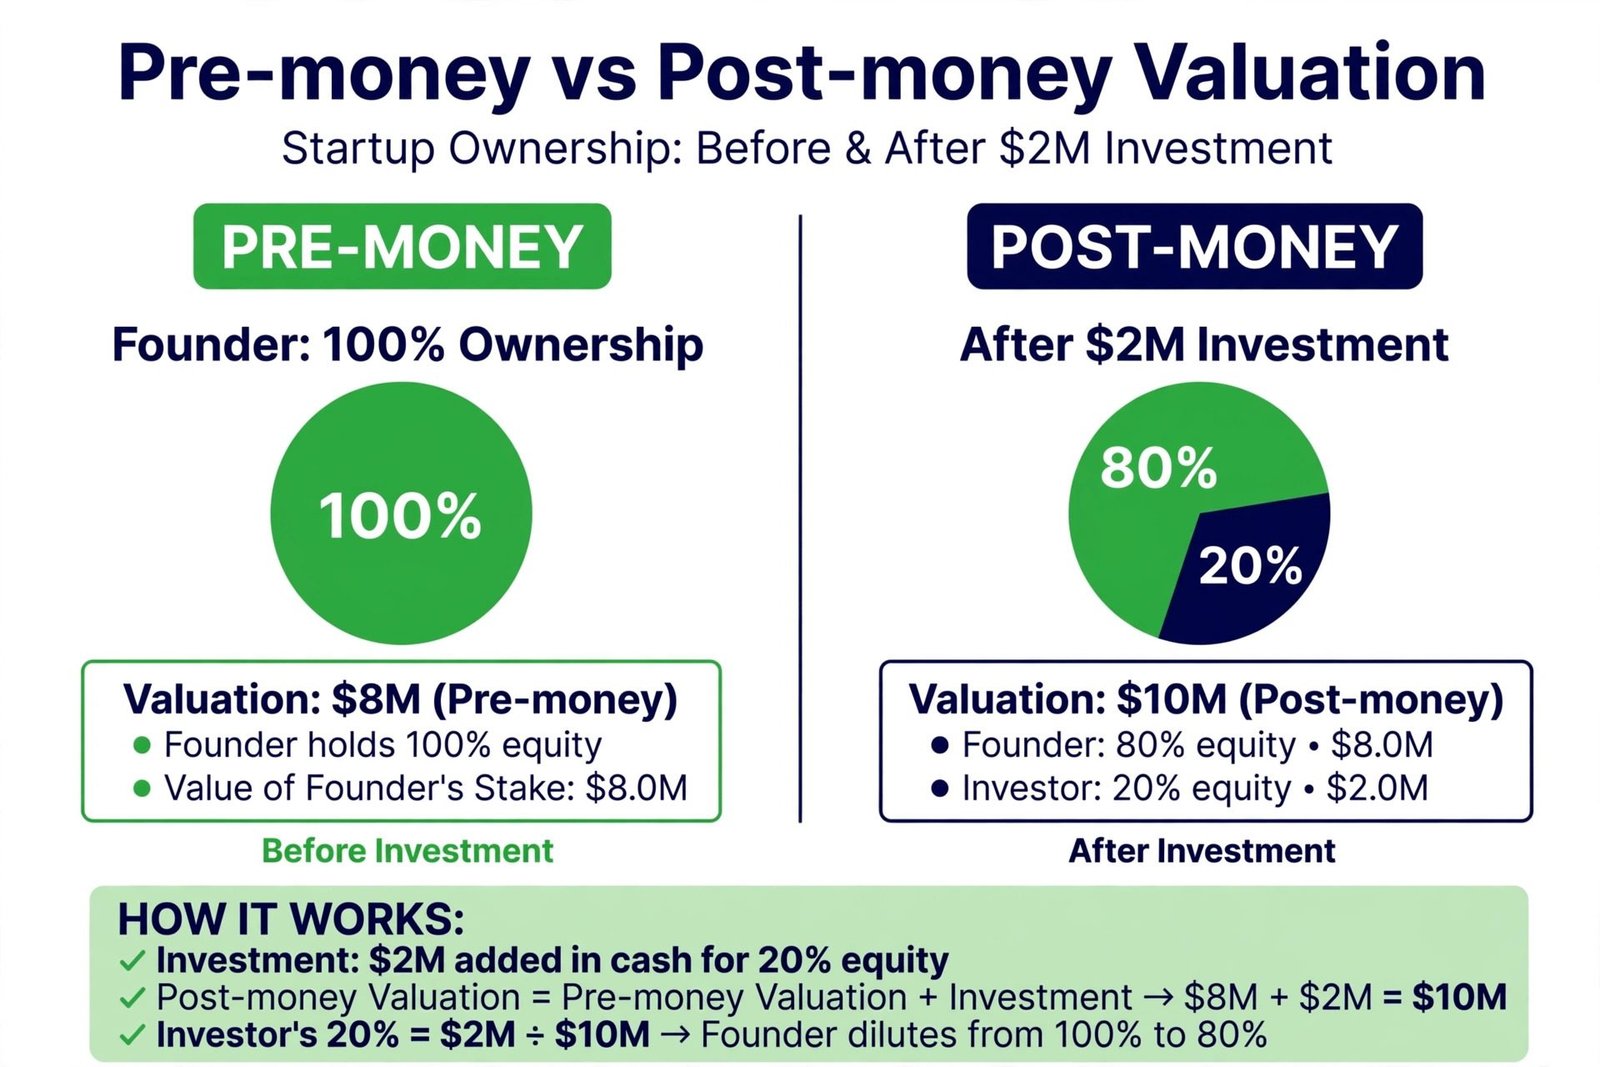
4. Pre-Money vs Post-Money: The Formula You Must Know Cold
This is where most founders make expensive mistakes — confusing pre-money and post-money valuation during term sheet negotiations. The distinction is simple but the consequences of getting it wrong are not.
📐 The Three Formulas Every Founder Must Know
Post-Money Valuation = Pre-Money Valuation + Investment Amount
Investor Ownership % = Investment ÷ Post-Money Valuation
Your Remaining % = Pre-Money Valuation ÷ Post-Money Valuation
A Real-World Negotiation Example
You are raising $1.5M. An investor offers a $6M pre-money valuation.
- Post-money = $6M + $1.5M = $7.5M
- Investor gets = $1.5M ÷ $7.5M = 20% of your company
- You keep = $6M ÷ $7.5M = 80%
Now you push back and negotiate to $9M pre-money:
- Post-money = $9M + $1.5M = $10.5M
- Investor gets = $1.5M ÷ $10.5M = 14.3%
- You keep = 85.7%
Same check. Same investor. Same round. 5.7% more of your company — just from understanding and defending the math. That single conversation, on a $100M exit, is worth $5.7M to you personally.
🔗
Choose the Right Instrument for Your Round
Once you have set your valuation, you need to decide whether to raise on a SAFE, convertible note, or priced equity round. Each has very different implications for your cap table. Read our full breakdown: SAFE Note vs Convertible Note: 2026 Founder Guide →
5. The 6 Factors That Move Your Valuation Up or Down
Regardless of which methodology you apply, these are the underlying signals that investors use to push your number higher or force it lower. Understand them. Optimize for them before you walk into any meeting.
📈 The Valuation Signal Map
📐
Market Size (TAM)
Is your addressable market genuinely $1B+? Investors need to see room for 10x growth within it.
📈
Growth Rate
Consistent MoM growth above 10–15% is a strong valuation multiplier. The shape of the curve matters more than the absolute number.
🏆
Team Pedigree
Ex-founders, domain experts, and repeat operators can add $1–3M to early-stage valuations purely on the credibility premium they carry.
🔒
Moat and IP
Proprietary technology, patents, exclusive data, or network effects that would take a competitor years to replicate.
💼
Customer Quality
Ten enterprise pilots outweigh a thousand free signups. Logo quality and contract value signal market validation more than raw user count.
🌍
Market Timing
Is regulatory change, new technology, or shifting behaviour creating a tailwind right now? Strong timing signals urgency — and urgency justifies a premium valuation.
🔍 The Hidden Factor Nobody Scores Formally
Every investor quietly runs a “founder-market fit” check that appears in no methodology. It answers one question: is this founder uniquely positioned to win this specific market — or could any competent person execute this idea? If the answer is “anyone could do this,” your valuation gets discounted even when every other metric looks strong. Prepare to explain clearly and specifically why you — not a well-funded rival — are the right person to build this company.
6. Realistic Valuation Ranges by Stage — 2026 Data
These are actual median ranges for 2026 based on global VC data. India-specific valuations run approximately 30–50% below US comparables at early stages, though the gap is narrowing fast in AI, SaaS, and fintech. Agritech is seeing particular momentum — a pattern visible in recent raises like Mitti Labs’ $9.5M Series A →
01
Pre-Seed
$1M – $5M Pre-Money
Idea stage to early MVP. Valuation driven almost entirely by team quality, market size, and concept strength. No revenue expected or required. Best methods: Berkus, Scorecard.
02
Seed
$5M – $16M Pre-Money
MVP live with early users or initial revenue. Global median in 2026 matched the 2021 all-time high of $16M. India seed stage typically runs $2M–$8M. Best methods: Scorecard, VC Method, Comps.
03
Series A
$20M – $60M Pre-Money
Proven product-market fit, $1M–$5M ARR, and a clear growth playbook. Global median hit a record $49.3M in 2026. Best methods: Revenue Multiple, VC Method, Comps.
04
Series B+
$80M – $300M Pre-Money
Scaling proven unit economics and entering new markets. Revenue multiples dominate. DCF analysis becomes relevant for the first time. Best methods: Revenue Multiple, DCF, Comps.
7. Five Valuation Mistakes That Kill Deals
❌
Mistake 1: Anchoring to a Round Number With No Methodology
“We are valued at $10M” with nothing behind it signals inexperience immediately. Investors will push back, and if you cannot defend the number, you lose credibility on everything else in the room. Always have two or three methods that independently support your figure.
❌
Mistake 2: Using Only TAM to Justify Your Ask
“The global market is $500 billion” tells investors nothing about the slice you can realistically capture. They want SAM and SOM — and a credible path to own your SOM within three to five years. TAM is the ceiling, not the justification.
❌
Mistake 3: Not Modelling Dilution Across Multiple Rounds
A $5M pre-money seed, followed by a $20M Series A, followed by a $60M Series B can leave you with under 30% of your company before you have hit scale. Model your cap table across three to four rounds before you sign any term sheet. Our related guide covers this: What Investors Want to See in a Pitch Deck →
❌
Mistake 4: Overvaluing Too Early and Getting Trapped
A $20M seed valuation sounds exciting until 18 months later when your metrics do not justify a $40–60M Series A. Down rounds are damaging, signal-destroying events that follow a company for years. A fair seed valuation with a clean up-round trajectory is worth far more than a flattering number today.
❌
Mistake 5: Pitching the Same Valuation Story to Every Investor Type
A seed-stage angel writing $25K checks thinks about valuation completely differently from a $300M Series A fund. Adjust your valuation narrative to match the mental model of who is across the table. For angels: Berkus method and a compelling story. For institutional VCs: VC method and clean exit math. Read more on VC psychology: 10 Secrets VCs Won’t Tell You About Raising Funding →
8. How to Present Your Valuation in a Pitch
The worst way to present your valuation: leading with the number. The best way: building the case so naturally that the number feels inevitable when you say it.
The 3-Step Valuation Narrative
Step 1 — Anchor on Market Reality
“Companies in our space at our stage are raising at $8–15M pre-money. Here are three comparable deals closed in the last 12 months.” Show the comps. Let the data do the anchoring.
Step 2 — Justify Your Position Above the Midpoint
“We are asking $12M pre-money — slightly above the median — because of [specific unfair advantage: team background, traction shape, proprietary moat]. Here is the data behind each point.”
Step 3 — Make Their Math Work
“At $12M pre-money and your $2M investment, you own 14.3%. If we hit our three-year plan and exit at $80M — which we believe is a conservative outcome for this market — that is a 5.7x return on your check.”
🎯
Give a Range, Not a Fixed Number
Presenting a valuation range — “$10M to $14M pre-money” — signals confidence and flexibility simultaneously. It invites negotiation rather than triggering a take-it-or-leave-it standoff. Psychologically it anchors the conversation above your floor. Founders who use this approach consistently close in the upper third of their stated range.
For a complete look at how valuation fits into your full fundraising story, read: How to Raise Seed Funding: 10 Proven Steps → and for building the deck around it: 7 Venture Capital Moves for New Ventures →
Ready to Build Your Pitch Around This?
Your valuation is only as strong as the pitch deck surrounding it. Use our free startup pitch deck template to structure your entire raise — from problem statement to the ask.
Get the Pitch Deck Template →The Bottom Line
Knowing how to value a startup is not a one-time exercise. It is an ongoing practice of understanding your market, your metrics, and the mental models of the people you are asking to bet on you.
The founders who raise the best rounds are not always the ones with the strongest products. They are the ones who can defend their number clearly, explain the methodology behind it, and make the math work for whoever is sitting across the table.
Pick two or three methods from this guide that match your current stage. Cross-validate them. Find where they agree. Then build your narrative around why your startup belongs at the upper end of that range — and practice defending every single number until you can answer any pushback without looking at your slides.
That is how investors value startups. Now you can too.

4 thoughts on “How to Value a Startup the Way Investors Do”
Comments are closed.